

Cannabis Tax Information
- What's New
- Overview of the Statewide Cannabis Tax
- Registration for the Statewide Cannabis Tax
- Filing Returns and Paying the Statewide Cannabis Tax
- Calculation of the Statewide Cannabis Tax
- Sales and Use Tax
- Municipal Level Cannabis Tax
What's New
Effective October 1, 2026, the Statewide Adult Use Cannabis Tax is no longer based on THC content: Legislation changed the tax that is based on the THC content of a product to a flat tax imposed at the rate of ten and seventy-five hundredths per cent (10.75%) of the gross receipts from all sales of adult use cannabis.
Overview of the Statewide Cannabis Tax
The statewide Cannabis Tax is based on single tax rate of 10.75% of a retailer’s gross receipts from adult use cannabis sales. Prior to October 1, 2026, Statewide Adult Use Cannabis Tax was imposed on milligrams of THC on retail sales of cannabis.
For more information regarding the statewide Cannabis Tax, please see Taxpayer Services Special Bulletin 2023-1, Frequently Asked Questions Concerning the Cannabis Tax.
Registration for the Statewide Cannabis Tax
To register for the statewide Cannabis Tax, each cannabis retailer, hybrid retailer, micro-cultivator must contact DRS at 860-297-4723, Monday through Friday, 8:00 a.m. to 4:30 p.m. or by contacting the agency’s primary point of contact for registration issues, Paul Silas. Registration questions may be emailed to Mr. Silas at: Paul.Silas@ct.gov
Filing Returns and Paying the Statewide Cannabis Tax
Each cannabis retailer, hybrid retailer, or micro-cultivator legally selling cannabis in Connecticut must file and pay the cannabis tax using myconneCT on the DRS website at portal.ct.gov/DRS-myconneCT. As outlined in the steps below, the return must be filed electronically and the tax due paid by electronic funds transfer.
- Log into myconneCT.
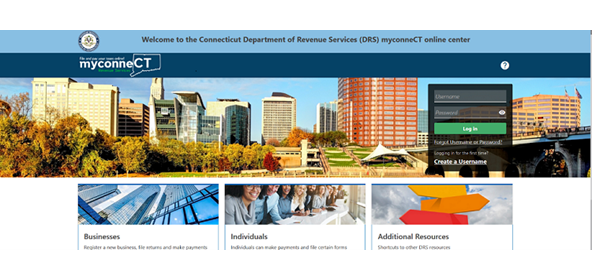
- From the Summary screen, the Cannabis Tax Return will be available.
- On the Cannabis Tax panel, click the File Now hyperlink.
- A confirmation email will be sent to indicate the return was successfully submitted.
Calculation of the Statewide Cannabis Tax
The statewide Cannabis Tax is based on a single tax of 10.75% of a retailer’s gross receipts from cannabis sales.
The statewide Cannabis Tax is in addition to the municipal level cannabis tax and the sales and use tax. The example below illustrates the application of all three taxes:
| Example: | Chocolate Bar |
| Sales Price: | $22.00 |
| Sales Tax (6.35%): | $ 1.40 |
| Municipal Level Tax (3.0%): | $ 0.66 |
| Statewide Cannabis Tax (10.75%) |
$ 2.37 |
| Total |
$26.43 |
Sales and Use Tax
Each sale of cannabis made by a cannabis retailer, hybrid retailer, or micro-cultivator that is subject to the statewide Cannabis Tax is also subject to the sales and use tax of 6.35%.
Municipal Level Cannabis Tax
Each sale of cannabis made by a cannabis retailer, hybrid retailer, or micro-cultivator that is subject to the statewide Cannabis Tax is also subject to the municipal level cannabis tax 3.0%.
Although DRS is not responsible for collecting the municipal level cannabis tax, the Department does play a role in the administration of this tax.
Each such municipality must provide contact information to DRS. Any and all questions related to the municipal level cannabis tax should be directed to the municipality in which the retailer, hybrid retailer, or micro-cultivator is operating.
Page Last Reviewed or Updated: 18-Sep-2026